WEEKLY MARKET DIGEST • September 28 – October 05, 2026
TLDR
- From the Sep 25 close to Oct 2: 10y +9bp, 30y +13bp, DXY +0.95%, while gold fell 3.68%.
- US payrolls increased by 29,000 in September, and unemployment rose to 4.2%.
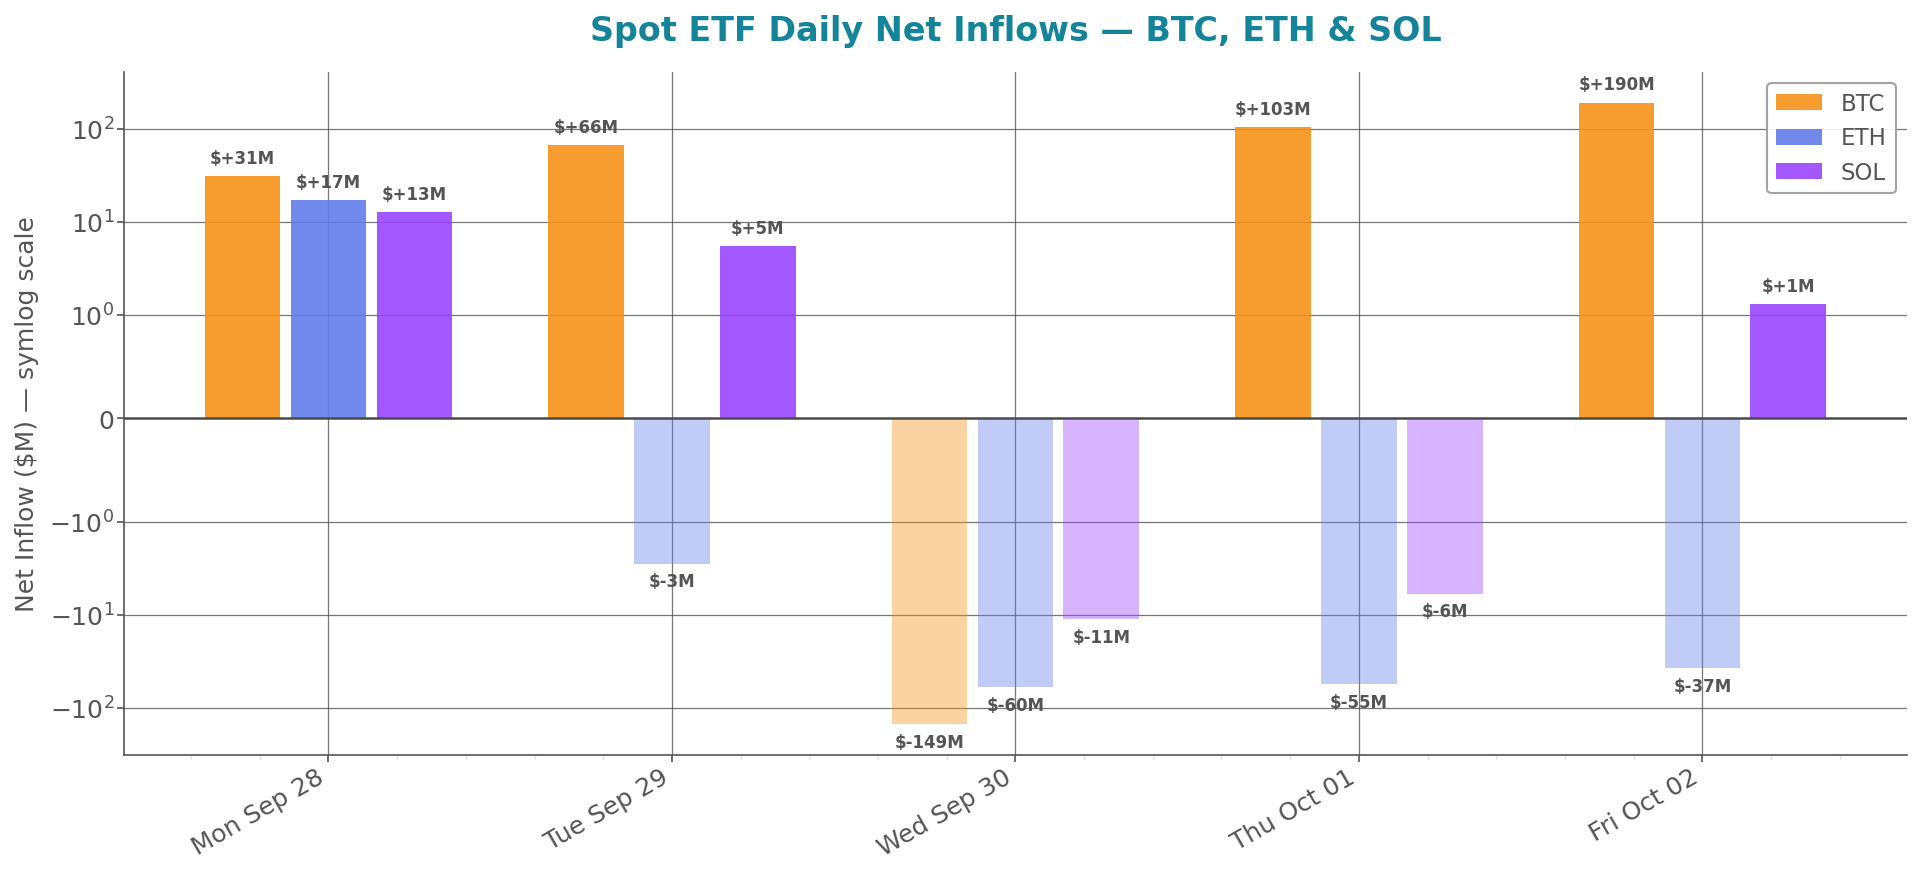
- Bitcoin gained as US spot BTC ETFs drew $241 million; ETH ETFs lost $138 million.
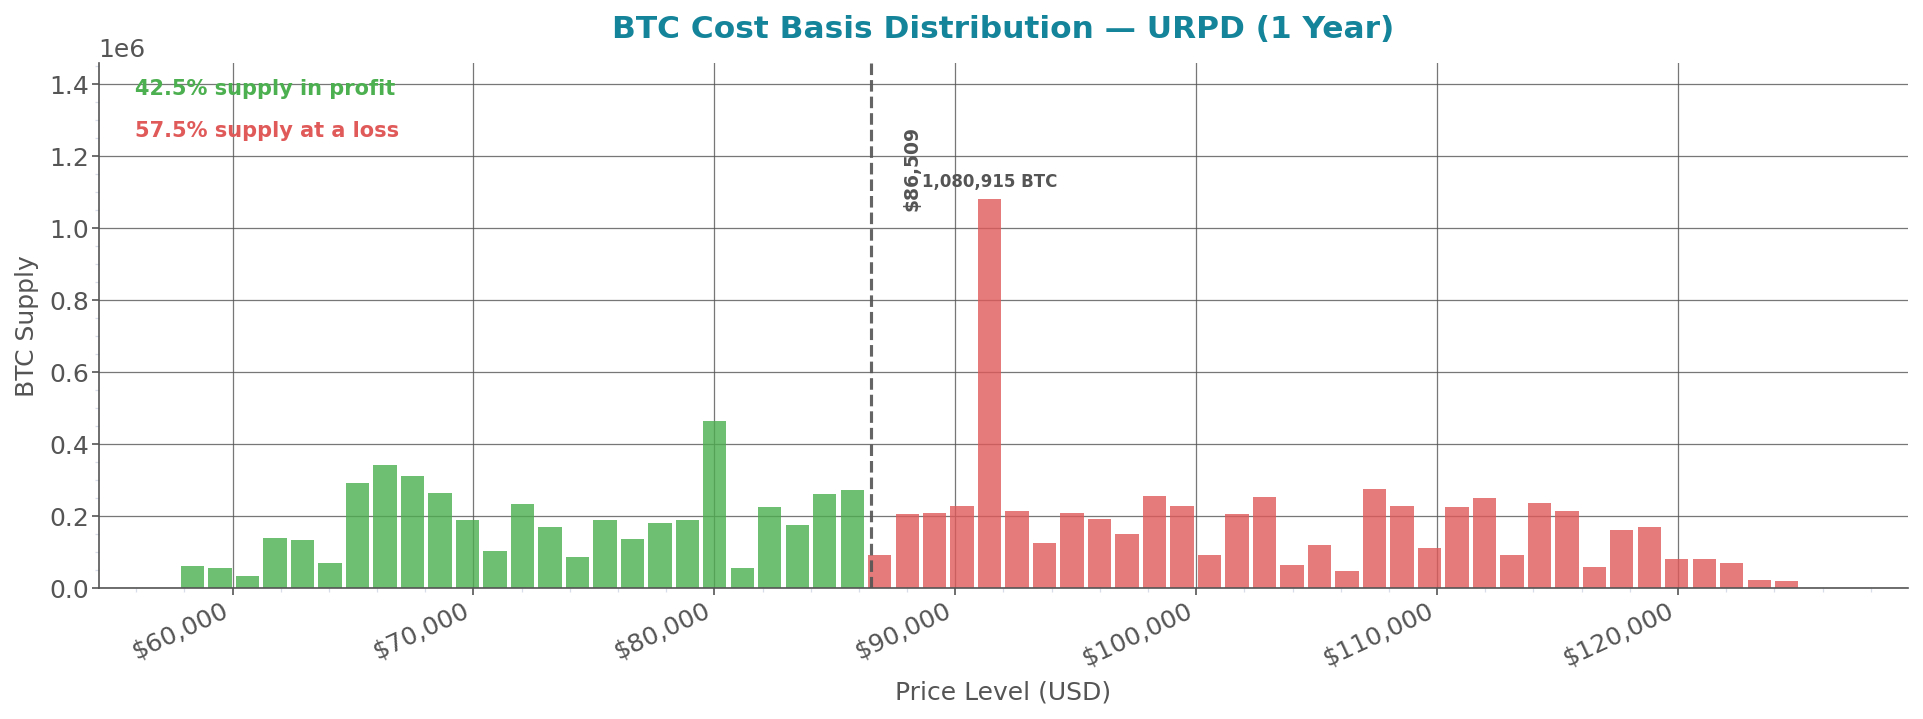
- Next week's key BTC downside level is $80,589, the largest nearby cost-basis cluster at 293,724 BTC.
Weekly Market Performance
| Asset | Week Open | Week Close | Weekly Change | 1M Change |
|---|---|---|---|---|
| Global Crypto Market Cap | $2.85T | $2.92T | +2.58% | — |
| S&P 500 | 7,743.41 | 7,722.72 | -0.27% | +0.05% |
| Dow Jones | 51,828.62 | 51,176.96 | -1.26% | -4.19% |
| Nasdaq | 27,068.72 | 27,190.86 | +0.45% | +2.58% |
| VIX | 14.87 | 15.31 | +0.44pp | +0.78pp |
| Bitcoin (BTC) | $83,118 | $85,817 | +3.25% | +7.74% |
| Ethereum (ETH) | $2,650 | $2,711 | +2.30% | +10.54% |
Macro Highlights
The US 10Y yield rose 9bp to 5.28% this week, driven by a global bond selloff on inflation fears. A softer jobs report on Oct 2 eased Fed rate hike concerns, but yields still ended the week higher. The dollar index closed at 101.93, up 0.95% on the week, while gold fell 3.68% to $4,162.30.
The September jobs report showed a significant slowdown in job growth, with nonfarm payrolls rising by 29,000 and the unemployment rate rising to 4.20%, leading traders to see little chance of a Fed rate hike in October.
(Bloomberg) (The New York Times) (CNBC)
Oil jumped more than 3% intraday on Monday, Sep 28, after President Trump rejected Iran's latest proposal to reopen the Strait of Hormuz, but WTI ended the week down 1.41% (Sep 25 close to Oct 2) after the G7 agreed to release up to 100 million barrels of oil and fuel over four months.
(Bloomberg) (CNBC) (Nasdaq)
US, French and other government bonds sold off sharply on inflation fears, while investors sought refuge in German debt, where Bund yields fell.
(Financial Times) (Bloomberg)
Week ahead
- FOMC minutes (Wed Oct 7): Markets will look for clues on how much support there was for the September hike and how policymakers view the path of further tightening.
- Consumer credit (Wed Oct 7): A sharp acceleration could suggest stronger household borrowing, but its implications for Fed policy are relatively indirect.
- Wholesale trade (Thu Oct 8): Stronger wholesale sales could point to resilient economic activity, but the signal for inflation and monetary policy is limited.
Crypto Highlights
Former SEC boss Jay Clayton has been appointed as the new AI Czar by Trump.
Zcash has activated its NU7 upgrade on testnet, a move that gives developers several weeks to assess the changes, including 25-second blocks, before the planned mainnet activation in November.
OKX and the NYSE parent have filed to launch a tokenized US stock platform, aiming to offer tokenized shares in over 60 US-listed companies, taking advantage of the SEC's recently introduced innovation exemption.
Greenfield Capital has asked the Swiss watchdog to intervene in a governance dispute with the Safe Ecosystem Foundation, after seeking changes to the foundation's board for months, according to the company's statement. The move by Greenfield Capital, a Safe investor, is aimed at resolving the long-standing dispute.
US Spot ETF Weekly Flows
| Fund | Weekly Net Flow | Cumulative Inflow | AUM |
|---|---|---|---|
| BTC Spot ETF | +$241.1M | +$57,809.2M | $108.89B |
| ETH Spot ETF | $-138.0M | +$13,801.9M | $17.46B |
| SOL Spot ETF | +$2.4M | +$1,607.8M | $1.90B |
Spot ETF Daily Flows — BTC, ETH & SOL
Cost Basis Distribution & Liquidation Exposure
BTC
ANALYST INTERPRETATION — BTC
1. Positioning & Derivatives Read
BTC rose from $83,118 to $85,817 over the week, a +3.25% week open-to-close move, while BTC ETFs took in +$241M in weekly net inflows. Glassnode reports $144M of BTC perp longs and $192M of BTC perp shorts liquidated over the week. The BTC long/short liquidation ratio (week total, longs ÷ shorts) was 0.75: more shorts were liquidated than longs this week. BTC positioning shows buyers adding through the ETF channel while BTC perp shorts absorbed more realised damage than BTC perp longs. BTC is under-extended rather than over-extended on this positioning read, but BTC goes into next week with the LONG side more exposed: exposure within 10% of BTC spot is $177M of shorts above and $192M of longs below, so the larger BTC cascade risk is below spot.
2. Key Risks & Levels for Next Week
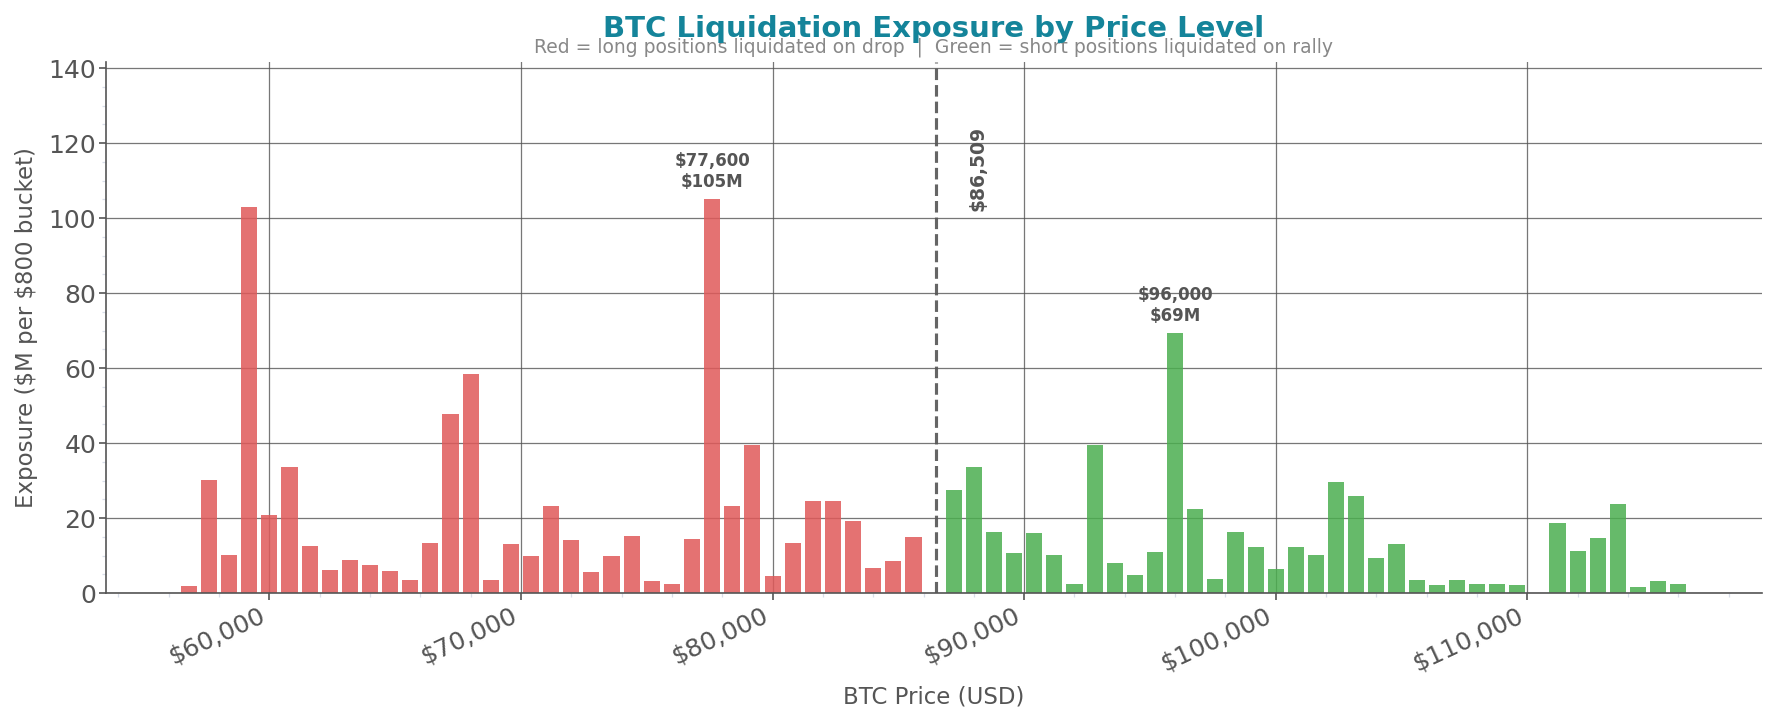
Upside Short Squeeze: BTC $90,960 is the heaviest nearby overhead cost-basis cluster, with 652129.94 BTC held at that level, and BTC $96,000 carries $69.3M of short liquidation exposure above BTC spot. The BTC risk is that ETF inflows keep absorbing supply into the $90,269 to $91,652 cost-basis zone while BTC perp short liquidations start accelerating before BTC reaches $96,000.
Near-Term Long Cascade: BTC $80,589 is the largest nearby downside cost-basis cluster, with 293724.26 BTC held at that level, and BTC $77,600 carries $105.0M of long liquidation exposure below BTC spot. The BTC risk is playing out if BTC spot volume expands on downticks, BTC ETF flows turn negative, and BTC perp long liquidation velocity rises before BTC reaches $77,600.
Deeper Downside Pocket: BTC $67,452 is the largest lower cost-basis cluster in the data, with 309953.17 BTC held at that level, and BTC $68,000 carries $58.5M of long liquidation exposure just above that cluster. The BTC warning signal is a shift in BTC options skew toward puts alongside persistent BTC ETF outflows and rising BTC spot sell volume before the move reaches the $68,000 liquidation band.
ETH
ANALYST INTERPRETATION — ETH
1. Positioning & Derivatives Read
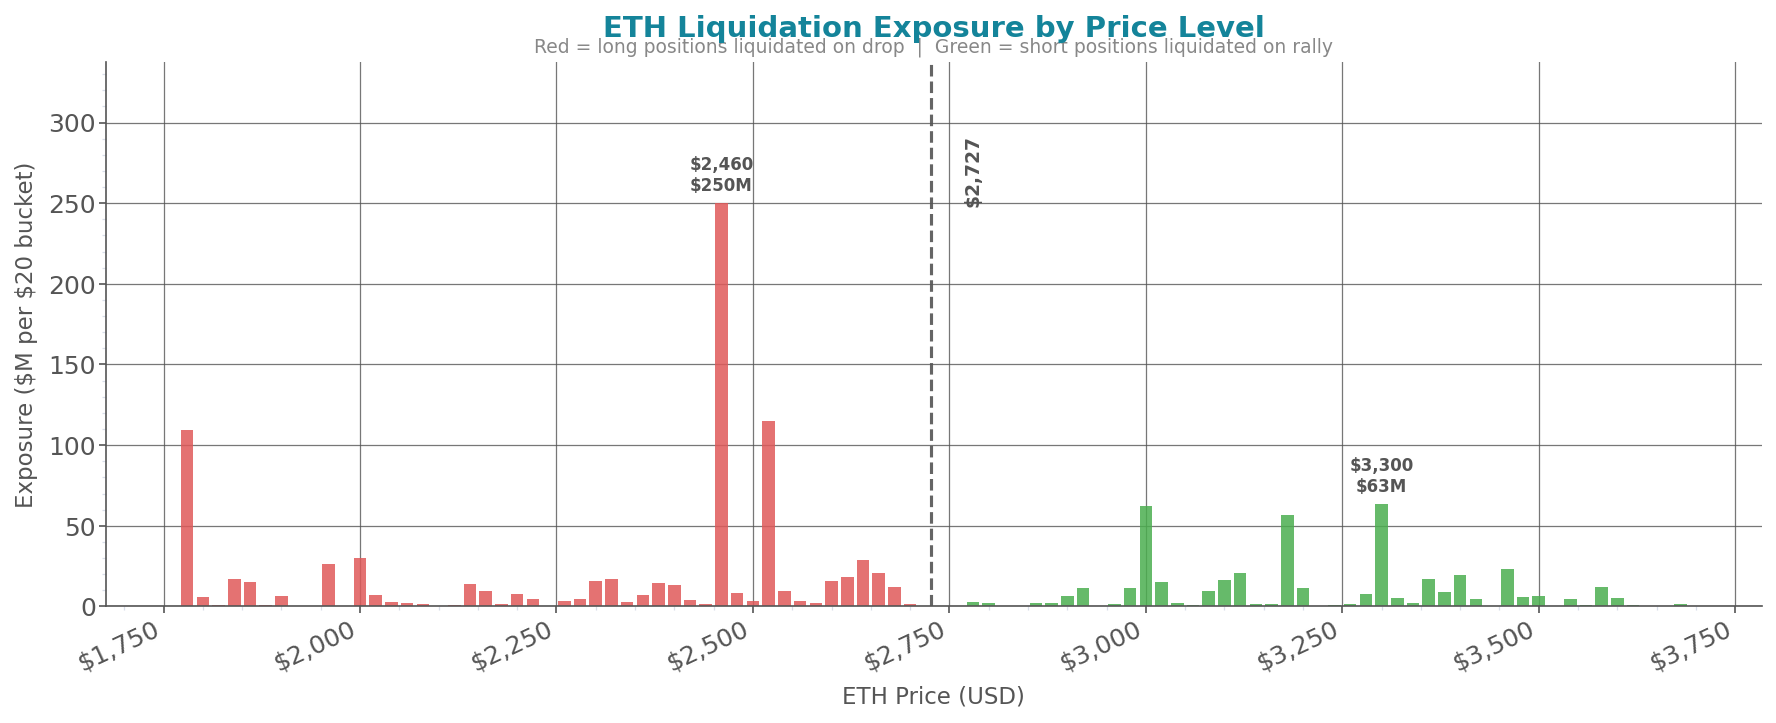
$130M of ETH perp longs and $130M of ETH perp shorts were liquidated this week, so realised pain was balanced rather than one-sided. The ETH long/short liquidation ratio for the week total was 1.00: longs and shorts were liquidated in roughly equal size this week. ETH ETF flows were negative at −$138M for the week, which means ETH gained +2.30% week open to close without ETF sponsorship. ETH perp liquidations peaked on Friday Oct 02 at $79M total, then Sunday Oct 04 skewed toward short pain with $1M of ETH perp longs and $19M of ETH perp shorts liquidated. ETH is not over-extended on realised perp positioning, but the next-week setup is asymmetrically exposed below ETH spot because the LONG side is the more exposed one, with $487M of longs below versus $39M of shorts above within 10% of ETH spot.
2. Key Risks & Levels for Next Week
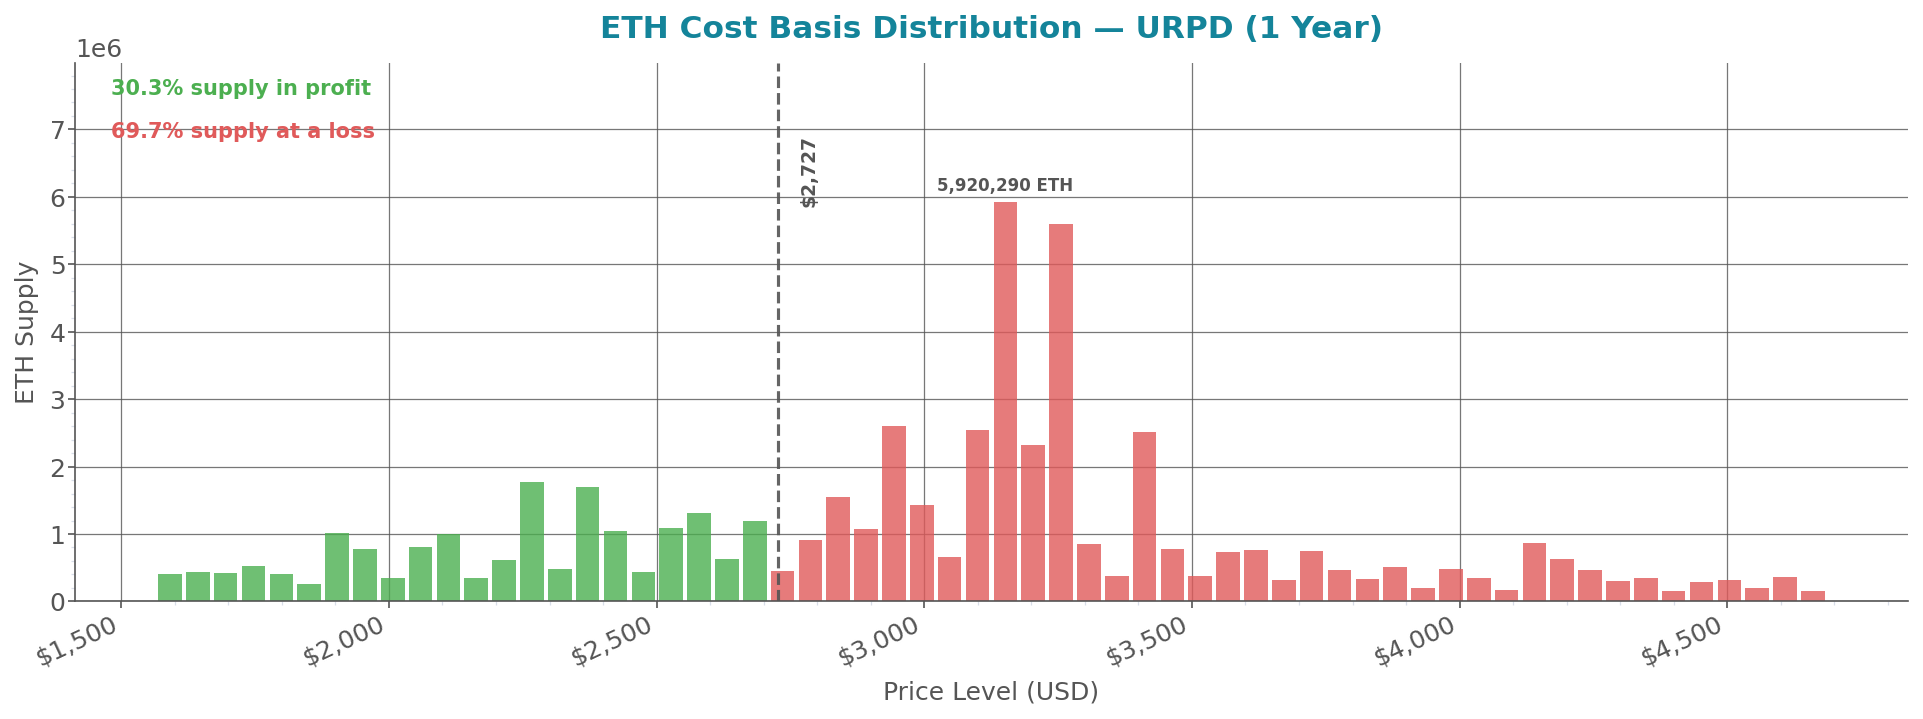
Downside Long-Liquidation Shelf: ETH has a nearby cost-basis support cluster at $2,574 with 670,756.28 ETH, followed by $115.2M of ETH long liquidation exposure at $2,520. The risk is that selling through the $2,574 holder base feeds directly into the $2,520 long-liquidation band. The tell is ETH spot volume expanding into weakness while ETH perp long liquidations accelerate before ETF flows turn positive.
Deeper Long Cascade: ETH has $250.2M of long liquidation exposure at $2,460, the largest long-liquidation band below current ETH price in the heatmap. The next major holder base sits at $2,385 with 1,344,979.17 ETH, so a liquidation-driven move into $2,460 would put a larger cost-basis cluster under pressure immediately after the perp flush. The signal is ETH options skew shifting toward puts while ETH liquidation prints increase in frequency rather than appearing as a single isolated flush.
Upside Short Squeeze Into Supply: ETH shorts have $62.0M of liquidation exposure at $3,000, but the heavier ETH supply overhead starts at $3,173 with 5,207,284.32 ETH at cost basis. That makes $3,000 the squeeze trigger area and $3,173 the first major test of whether spot demand can absorb trapped supply. The signal is ETH ETF flows flipping positive while ETH spot volume rises and ETH perp short liquidations accelerate into the move.
On-Chain Signals — Bitcoin
| Signal | Week-End | Week Chg | Reading |
|---|---|---|---|
| MVRV Ratio | 1.643 | +3.4% | Moderate gains phase |
| NUPL | 0.396 | +5.4% | Optimism |
| Exch. Net Flow (week total) | -26,810.5 BTC | +8,043.2 BTC | Net outflows — accumulation |
| Exchange Balance (USD) | $288.17B | +3.0% | |
| Perp Funding Rate | +0.00565% | +0.00155pts | Near-neutral |
| Perp Open Interest | $36.02B | +4.8% | |
| 1M Implied Vol | 34.6% | -0.4pts | Low vol environment |
| 25Δ Put/Call Skew | -0.7% | -2.6pts | Neutral |
| Realized Vol (1W) | 24.3% | -7.9pts | Moderate |
| DVOL Index | 36.5 | +1.6% | |
| Accumulation Balance | 2,017,093 BTC | +0.5% | |
| Supply Held ≥100k BTC | 729,349 BTC | +0.0% | |
| Net Realized P/L (week total) | +$3,202.6M | -$2,225.1M | Coins moved at a profit |
Amber rows deviate >1.5σ from prior 4-week baseline • data as of 2026-10-04
BTC is in a mid-cycle profit regime: MVRV 1.643 (+3.4%) and NUPL 0.396 (+5.4%) sit 1.9σ and 1.7σ above 4-week baselines, indicating rising unrealized gains short of euphoric levels. Positioning risk is moderate but building, with funding at +0.00565% and perp OI up 4.8% to $36.02B, while 1M IV at 34.6%, 1W realized vol at 24.3%, and -0.7% skew imply cheap vol and little downside demand.
Weekly Market Wrap
The week was defined by dispersion under a firmer dollar and a renewed rates scare: the US 10y +9bp, US 30y +13bp, DXY +0.95%, and gold -3.68% on the week. That tightening in the cross-asset backdrop did not produce a single risk-off tape, but it did punish duration-sensitive and cyclical pockets while leaving select growth and crypto bid. The S&P 500 slipped 0.27%, the Dow lost 1.26%, and the Nasdaq gained 0.45%, while VIX +0.44pp showed only a modest pickup in hedging demand. Bitcoin rose 3.25% and Ethereum added 2.30%, making digital assets one of the few major risk segments to close the week higher.
US equities finished mixed as leadership narrowed toward AI and chips, lifting the Nasdaq 0.45% while the Dow lost 1.26%. Nvidia, TSMC and ASML all rose, but the chip trade was not uniform, with Qualcomm down 8.47% and Intel down 2.98%. Financials took the heaviest selling, with JPMorgan and Goldman Sachs each down more than 3% and Bank of America off 5.20%, and Apple's 2.16% slide kept the rest of mega-cap tech from joining the rally. The macro tape was unusually busy: US consumer spending rose 0.6% in August in real terms, Kashkari said inflation was "still too high," payrolls increased by 29,000 in September and unemployment rose to 4.2%, and the US and China lowered tariffs on $60 billion of goods even as Washington escalated against Canada on dairy and liquor. Europe was weaker as political and fiscal pressure hit the euro, with EUR/USD down 1.26%; the CAC 40 fell 2.24%, FTSE 100 2.18%, FTSE MIB 2.67%, IBEX 35 3.12%, and BEL 20 3.48%. China's factory activity returned to growth, but the Hang Seng still fell 2.19%; Japan's TOPIX ETF was nearly flat at -0.02%. WTI crude lost 1.41% after OPEC+ kept November output targets steady and Saudi Arabia cut benchmark pricing to Asia.
Crypto's week was defined by resilient majors, a sharp slowdown in ETF demand, and another round of security and regulatory stress. Bitcoin rose from $83,117.75 to $85,816.53, up 3.25% on the week, while Ethereum advanced from $2,650.33 to $2,711.35, up 2.30%, and Solana gained 1.72%. US spot Bitcoin ETFs took in $241 million over the week, a fraction of the roughly $2.4 billion they drew the week before, while Ether funds recorded outflows of $138 million. Strategy bought 1,665 Bitcoin for $143 million, taking its holdings to 847,666. Regulation remained active: Coinbase received CFTC approval for a US derivatives clearinghouse, the SEC proposed removing custody hurdles for advisers offering crypto, Hong Kong expanded reporting oversight for licensed virtual asset providers, and New York and Wyoming agreed to coordinate crypto supervision. Security was the week’s main blemish: Bitget’s $388 million breach dominated September’s $768 million hack tally, NEAR Intents blocked $50 million tied to the Bitget hackers but then suffered and recovered a $3.8 million exploit, and MetaMask exited Ethereum validators after an undisclosed security incident.
Next week’s key crypto catalyst is Ethereum’s Glamsterdam upgrade on Sepolia on October 6, with proposer-builder separation and new gas pricing in focus before any mainnet timetable is set. Markets will also watch whether the SEC engages with the OKX and NYSE-parent filing for tokenized shares in more than 60 US-listed companies under the innovation exemption, after tokenized markets reached $34.5 billion in RWA value and BNB Chain crossed $1.1 billion in tokenized stocks and ETFs. On macro, the follow-through from September payrolls, European political stress after the euro’s 17-month low, and the market reaction to OPEC+ holding November targets steady will set the tone after a week in which rates, the dollar, and regional equity divergence did most of the talking.