WEEKLY MARKET DIGEST • September 14 – September 21, 2026
TLDR
- Bitcoin rose 5.59%
- VIX fell 1.03pp
- 10Y Treasury: 5.01% (+5 bp w/w)
- $193M BTC perp longs liquidated
Weekly Market Performance
| Asset | Week Open | Week Close | Weekly Change | 1M Change |
|---|---|---|---|---|
| Global Crypto Market Cap | $2.64T | $2.80T | +6.12% | — |
| S&P 500 | 7,656.98 | 7,650.50 | -0.08% | -0.31% |
| Dow Jones | 52,573.29 | 51,682.64 | -1.69% | -2.99% |
| Nasdaq | 26,333.04 | 26,522.54 | +0.72% | +1.31% |
| VIX | 15.84 | 14.81 | -1.03pp | -0.32pp |
| Bitcoin (BTC) | $77,440 | $81,771 | +5.59% | +5.94% |
| Ethereum (ETH) | $2,512 | $2,669 | +6.24% | +10.26% |
Macro Highlights
Fed Hikes Rates
The Federal Reserve has raised the fed funds rate, with most policymakers projecting one additional hike this year. The Federal Reserve approved an interest rate hike on Wednesday, September 16, with Chairman Kevin Warsh highlighting persistent inflation risks. The rate hike reinforces the Fed’s more restrictive policy stance and could keep upward pressure on U.S. Treasury yields, particularly if markets expect rates to remain higher for longer.
US-China Talks
The US and China have held constructive talks on trade, investment and AI ahead of a summit between Donald Trump and Xi. US and Chinese officials offered upbeat assessments of the talks on Monday, September 21, with both sides agreeing to continue economic and AI dialogue ahead of the summit. A constructive outcome from the talks could reduce demand for safe-haven assets such as gold and the dollar as investors shift toward riskier assets. This could support emerging-market equities and currencies, particularly if the talks produce concrete progress on tariffs, trade and investment. However, the dollar may remain supported by the Fed's hawkish policy stance, limiting any downside from improving U.S.-China relations.
Oil Supply Disruptions
Oil prices have been volatile amid supply disruptions linked to attacks on Saudi oil infrastructure, Houthi activity and disruptions to shipping in the Gulf. Oil extended gains on Tuesday, September 15, following reports of fresh Houthi strikes, but prices fell on Friday, September 18, as additional Saudi crude supplies eased disruption fears. Further disruptions to Middle Eastern oil supplies could push crude prices higher and add to inflationary pressure, particularly if the disruptions persist. A sustained oil-price shock could reinforce expectations for a more restrictive Fed policy stance, supporting Treasury yields and potentially the dollar.
Bank of Japan Rate Hike
The Bank of Japan has raised interest rates to a 31-year high, citing inflation risks, with two dissenting votes signaling less agreement over the pace of further policy tightening. The Bank of Japan lifted interest rates by 0.25 percentage points to 1.25% on Friday, September 18, with board members Toichiro Asada and Ayano Sato dissenting from the hike. The rate hike increases the potential for further yen appreciation by narrowing the interest-rate differential with overseas markets. However, the two dissenting votes tempered expectations for rapid further tightening, and the yen initially weakened after the decision. This suggests that the pace of future BOJ hikes, rather than the 25 bp increase itself, will be important for the yen and Japanese assets.
(CNBC) (Financial Times) (Bloomberg)
Week ahead
- US-China summit — September 24: The Trump-Xi summit will be the main geopolitical event of the week. A constructive outcome on trade, tariffs and investment could support risk appetite and emerging-market assets, while reducing demand for safe-haven assets. The focus will be on whether the meeting produces concrete progress while maintaining stability in bilateral relations.
- US economic data — September 23–25: The September flash PMIs, August new-home sales and August durable-goods orders will provide fresh signals on the strength of the US economy. Stronger-than-expected data could reinforce expectations for a higher-for-longer Fed policy stance, supporting Treasury yields and the dollar; weaker data could have the opposite effect.
- Fed speakers — throughout the week: Several Fed officials, including John Williams, Philip Jefferson and Michelle Bowman, are scheduled to speak. Their comments will be closely watched for clues about the timing and extent of further tightening following last week's 25 bp rate hike.
- FOMC minutes — October 7: The minutes from the September 15–16 FOMC meeting are not due this week; they are scheduled for October 7. The minutes could provide further detail on the debate around additional rate hikes and influence expectations for Treasury yields and the dollar.
Crypto Highlights
The US Senate failed to advance the CLARITY Act, leaving the legislation facing an uncertain future after months of negotiations over crypto oversight and ethics provisions. The CLARITY Act's passage odds have dropped to 16% as key Democrats push back against the GOP's latest proposal. The US Commodities Futures Trading Commission (CFTC) has submitted a new crypto market regulatory plan for review by the White House, days after the Senate failed to advance the CLARITY Act.
Bitcoin has reclaimed its 50-week moving average, a move that has historically marked the end of bear markets, but analysts caution that one weekly close above this threshold is not enough to confirm a new bull run.
Hana Bank has utilized Euroclear's blockchain technology to issue a $100M bond, resulting in a significant reduction in settlement time from three to five business days to the same day.
North Korean cyber group WaterPlum has been found to infect at least 30,000 devices across more than 100 countries, stealing $10.7M in crypto, by targeting developers with fake job offers at crypto, AI, and NFT companies.
US Spot ETF Flows
| Fund | Weekly Net Flow | Cumulative Inflow | AUM |
|---|---|---|---|
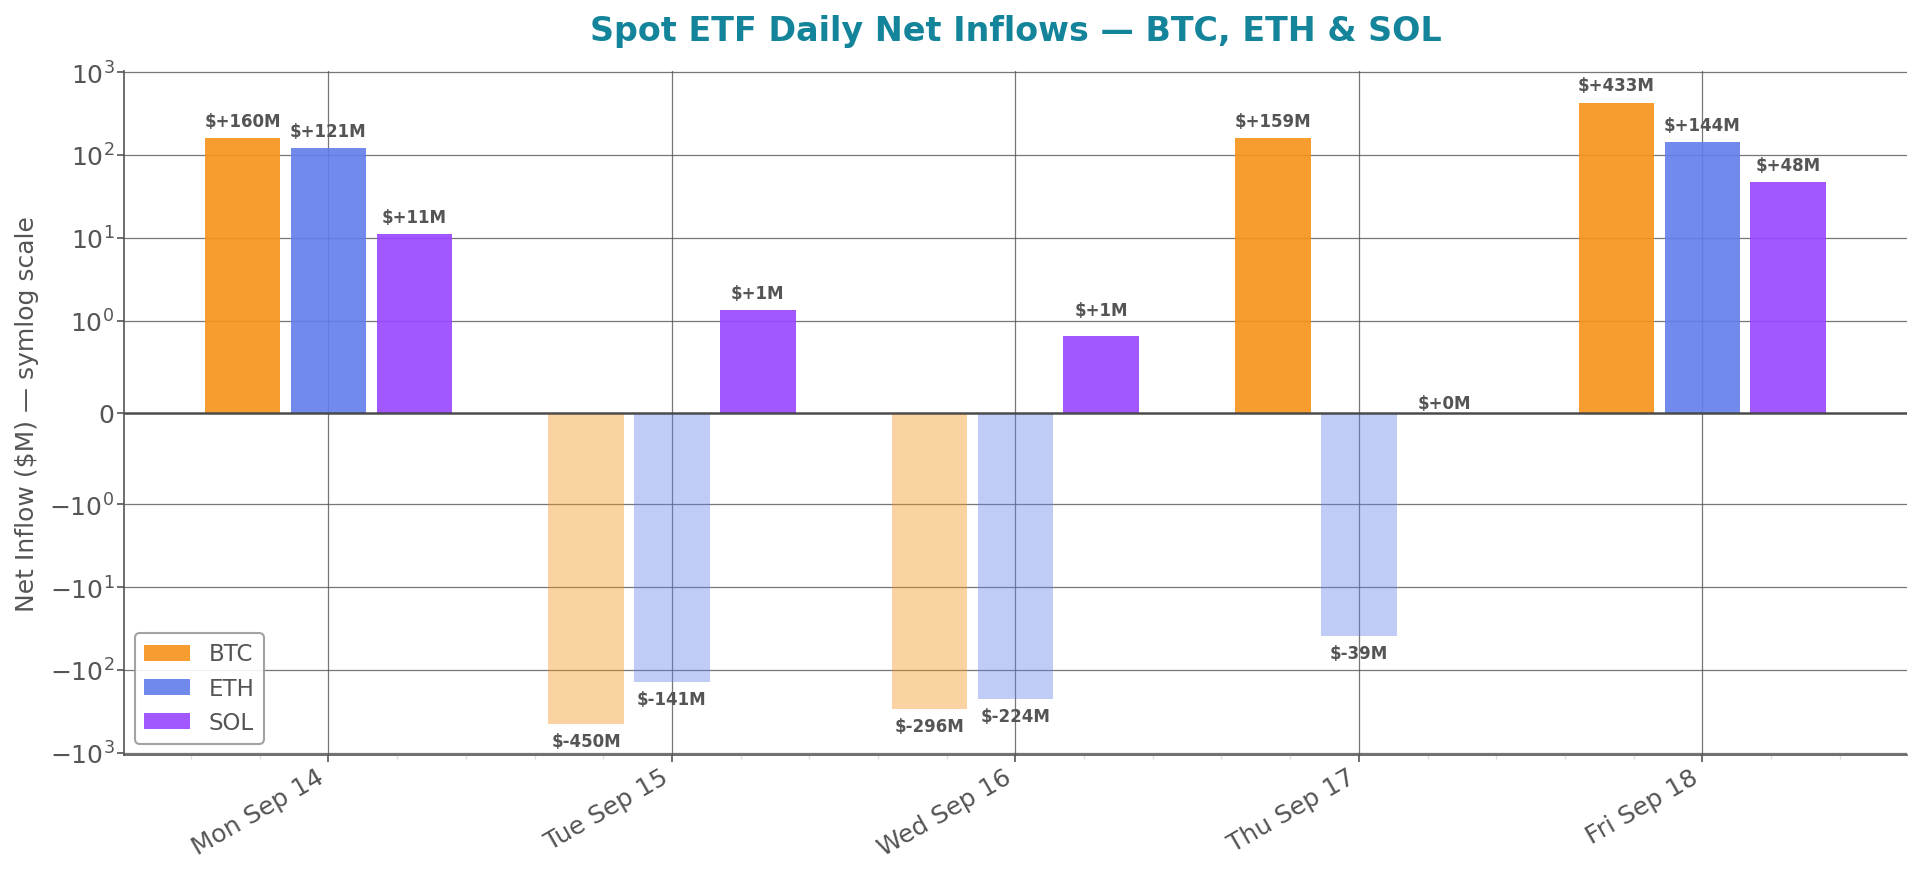
| BTC Spot ETF | +$6.2M | +$55,182.3M | $102.53B |
| ETH Spot ETF | $-140.0M | +$13,250.0M | $16.72B |
| SOL Spot ETF | +$60.8M | +$1,417.1M | $1.62B |
Spot ETF Daily Flows — BTC, ETH & SOL
Cost Basis Distribution & Liquidation Exposure
BTC
ANALYST INTERPRETATION — BTC
1. Positioning & Derivatives Read
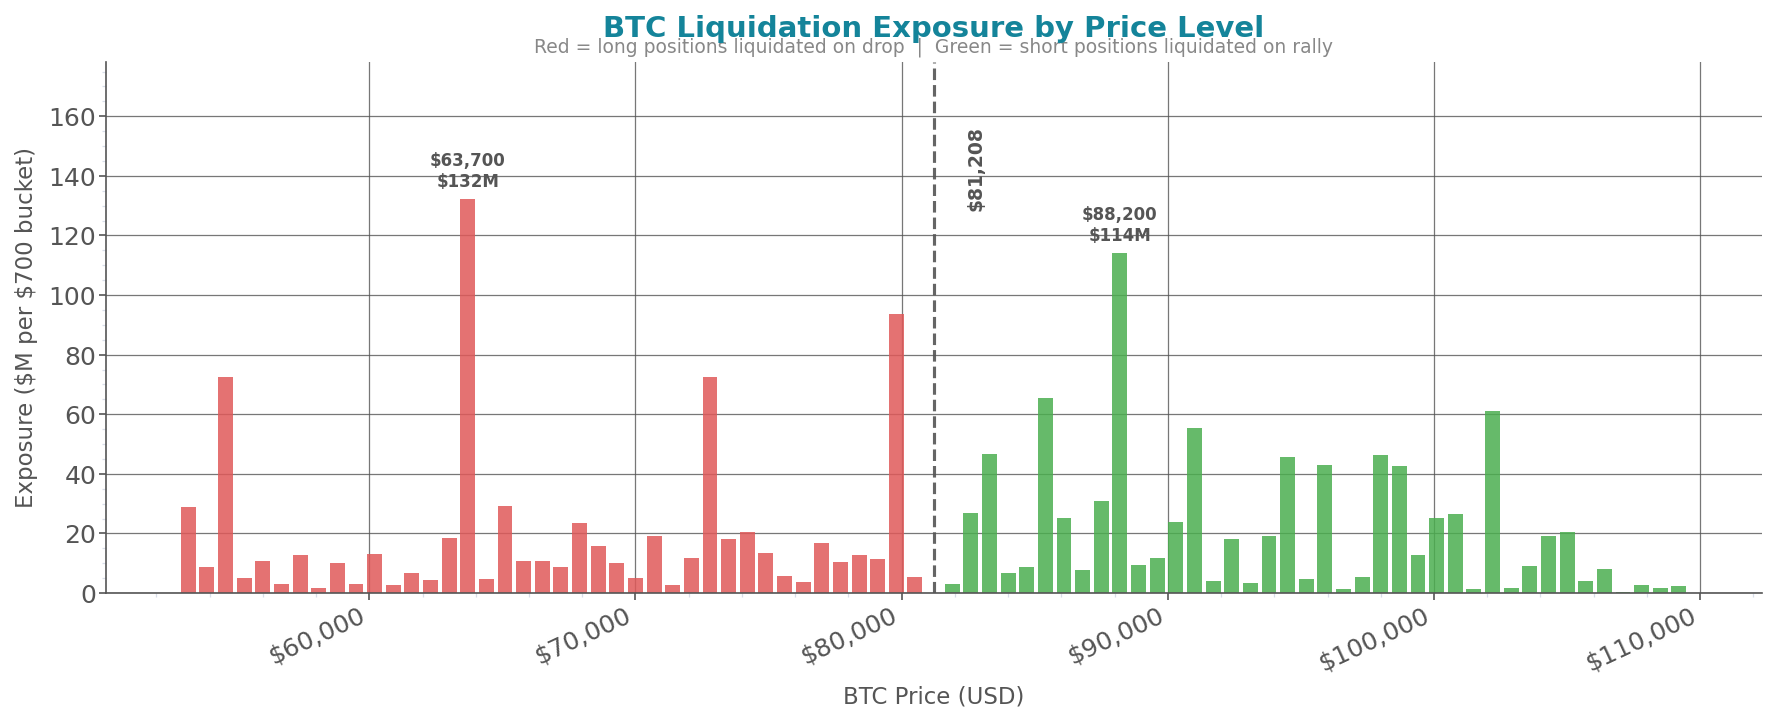
$193M of BTC perp longs were liquidated, while $263M of BTC perp shorts were liquidated, with a long/short liquidation ratio of 0.74, indicating that short positions accounted for the larger share of liquidations. The ETF flow direction and magnitude show a weekly net flow of +$6M into BTC, suggesting continued investor interest. Based on the liquidation exposure in the on-chain levels, positioning appears asymmetric, with $345M of short exposure above BTC spot compared with $213M of long exposure below.
2. Key Risks & Levels for Next Week
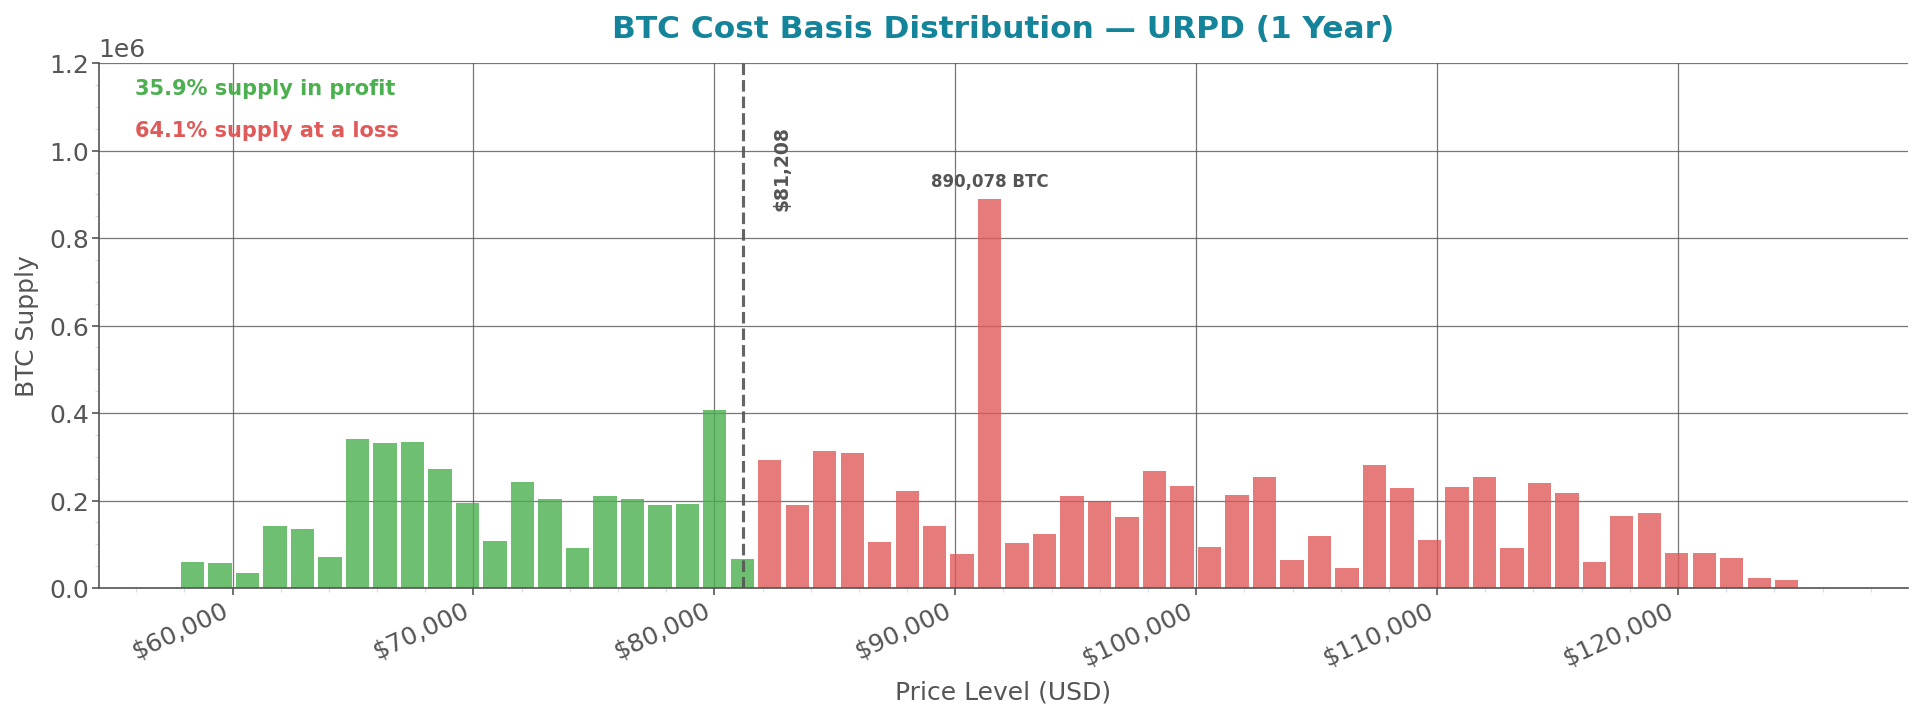
Rally Risk: A nearby supply cluster sits at $82,663, with 181,402 BTC concentrated around that cost basis, which could act as near-term resistance. Above spot, short liquidation exposure increases as BTC moves higher, with approximately $65.5M of exposure in one of the larger liquidation bands and substantially more at higher levels. Watch for spot volume to accelerate as price approaches these levels, which would provide confirmation of a sustained move.
Drop Risk: The $80,589 area represents a significant cost-basis cluster below BTC spot and could act as support. If BTC breaks below this area, attention would shift toward the larger long-liquidation concentrations below, including approximately $93.7M of exposure around $79,800.
Liquidation Risk: The $79,800 level has approximately $93.7M of long liquidation exposure. A move toward this level could increase liquidation pressure, particularly if accompanied by accelerating spot volume. Monitor liquidation rates and spot volume around the level for signs of a potential cascade.
ETH
ANALYST INTERPRETATION — ETH
1. Positioning & Derivatives Read
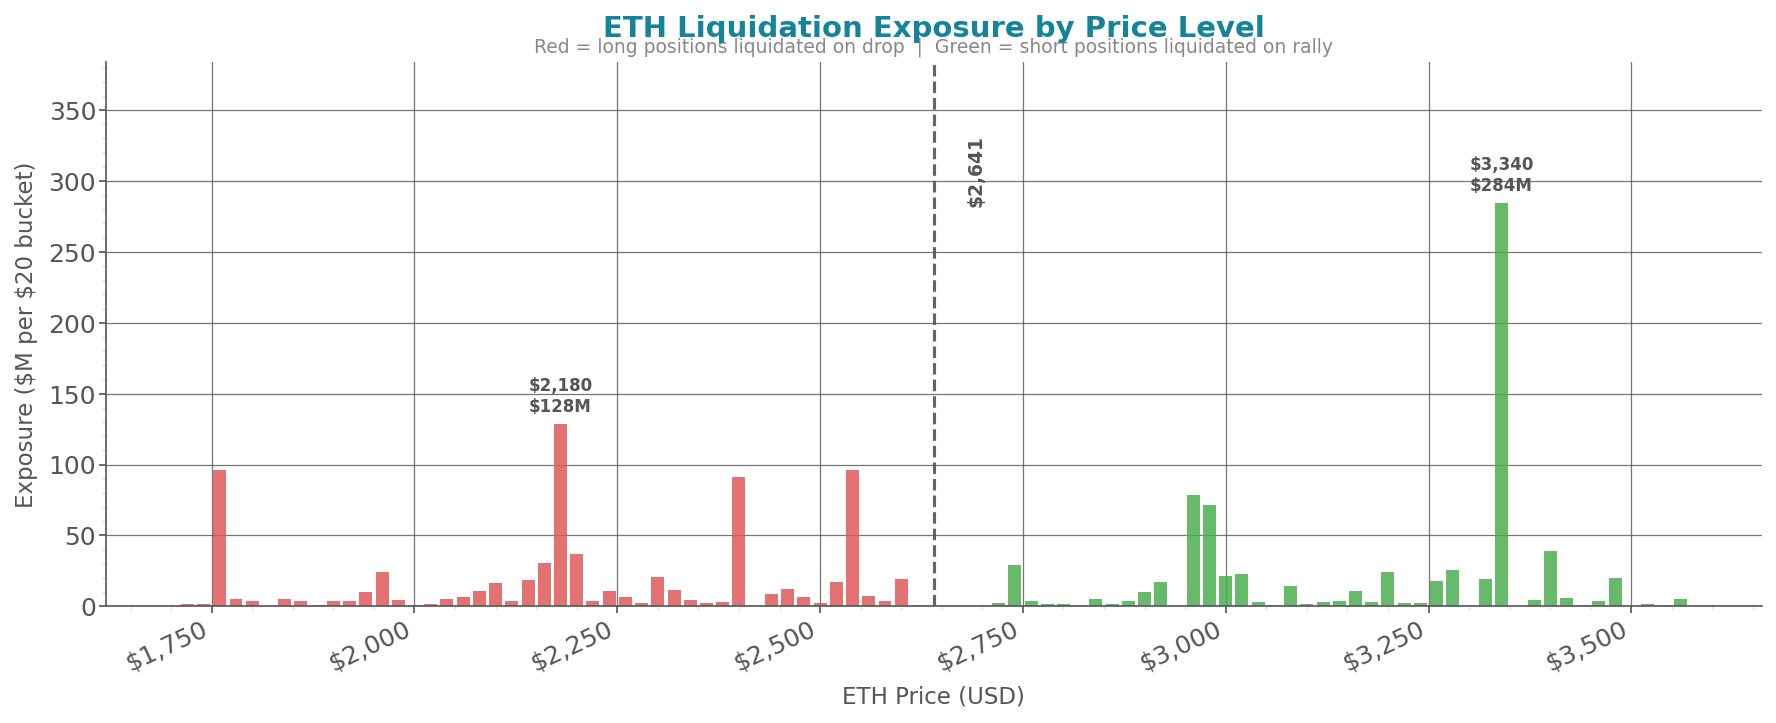
ETH perpetual longs were liquidated for $198M and shorts for $236M, with a long/short liquidation ratio of 0.84, indicating that short positions accounted for the larger share of liquidations. ETH ETF flows were negative, with a weekly net flow of -$140M, suggesting net investor outflows over the week. Combined with the liquidation exposure below spot, positioning appears more vulnerable on the downside, with approximately $271M of long liquidation exposure below ETH spot. The exposed side is therefore the long side, with substantially more liquidation exposure below spot than on the corresponding short side above spot.
2. Key Risks & Levels for Next Week
Liquidation Risk: The largest identified long-liquidation concentration below ETH spot is around $2,180, with approximately $128.4M of exposure. A move toward this level could increase liquidation pressure as leveraged longs are forced to close. Monitor liquidation rates and spot volume around the level for signs of a potential cascade.
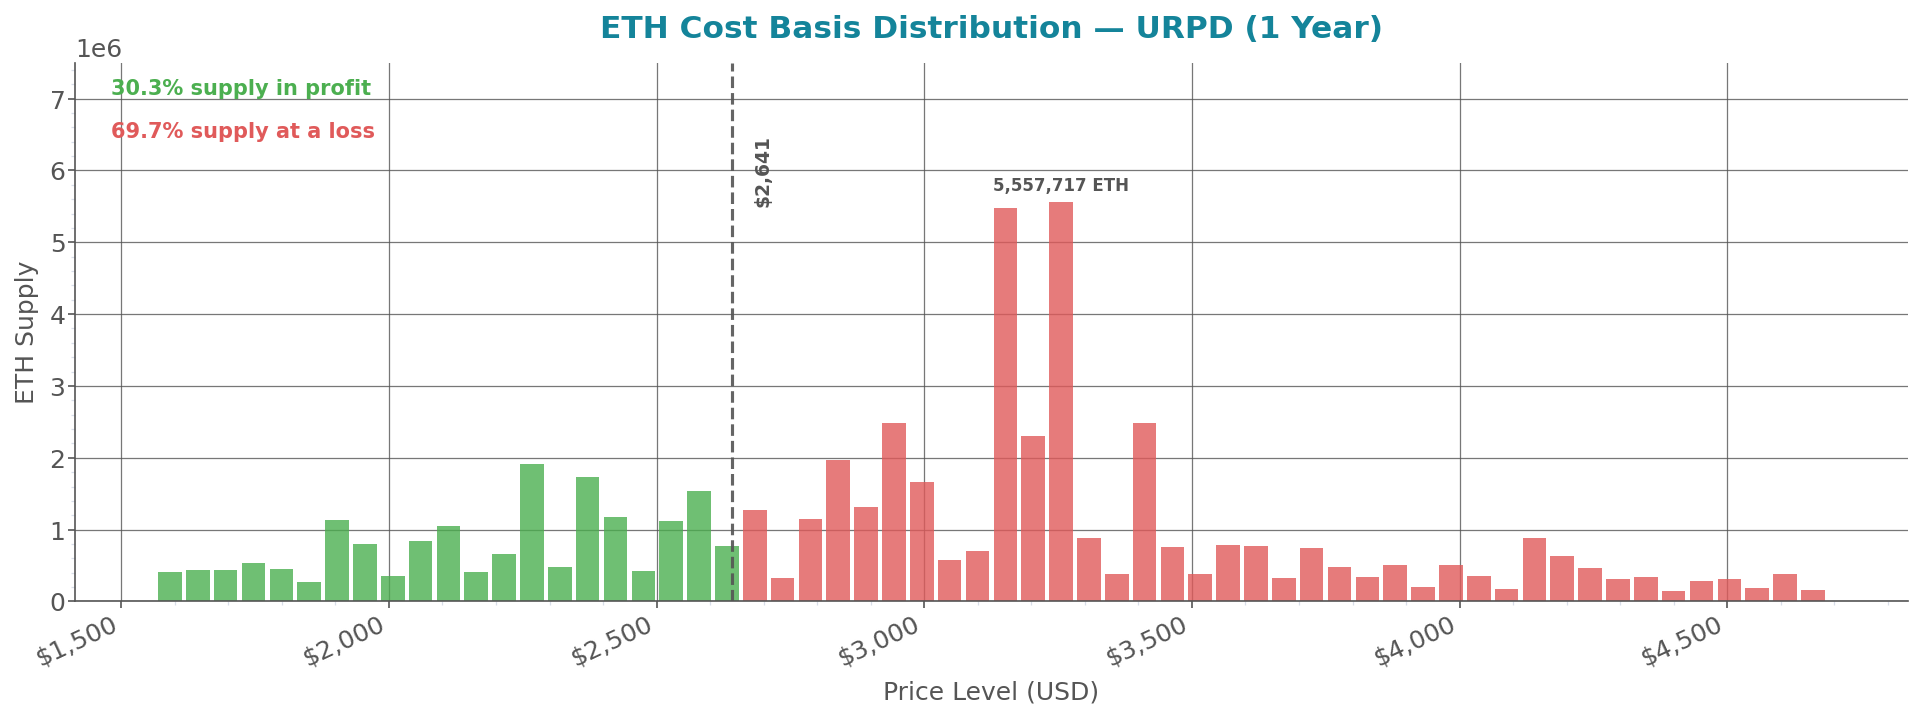
Support Break Risk: A significant cost-basis cluster sits around $2,574, with approximately 832K ETH concentrated at this level. A sustained break below this area could weaken near-term support and expose ETH to the larger liquidation concentrations below. Watch for accelerating ETF outflows, spot selling volume and perp liquidations as confirmation that downside pressure is increasing.
Rally Risk: The largest identified short-liquidation concentration above ETH spot is around $3,340, with approximately $284.5M of short exposure. A sustained move toward this level could trigger forced short covering and amplify upside momentum. Monitor spot volume and perp liquidation rates for evidence of a short squeeze, while a shift in options skew toward calls would provide additional evidence of increasing upside demand.
On-Chain Signals — Bitcoin
| Signal | Week-End | Week Chg | Reading |
|---|---|---|---|
| MVRV Ratio | 1.551 | +3.7% | Moderate gains phase |
| NUPL | 0.365 | +7.0% | Optimism |
| Exch. Net Flow | +717.1 BTC | -1,511.2 BTC | Net inflows — distribution |
| Exchange Balance (USD) | $270.31B | +4.1% | |
| Perp Funding Rate | +0.00654% | +0.00296pts | Near-neutral |
| Perp Open Interest | $36.65B | +7.6% | |
| 1M Implied Vol | 34.4% | -2.3pts | Low vol environment |
| 25Δ Put/Call Skew | 3.8% | +2.3pts | Neutral |
| Realized Vol (1W) | 44.0% | +22.9pts | Elevated |
| DVOL Index | 35.66 | -7.5% | |
| Accumulation Balance | 2,011,390 BTC | -0.1% | |
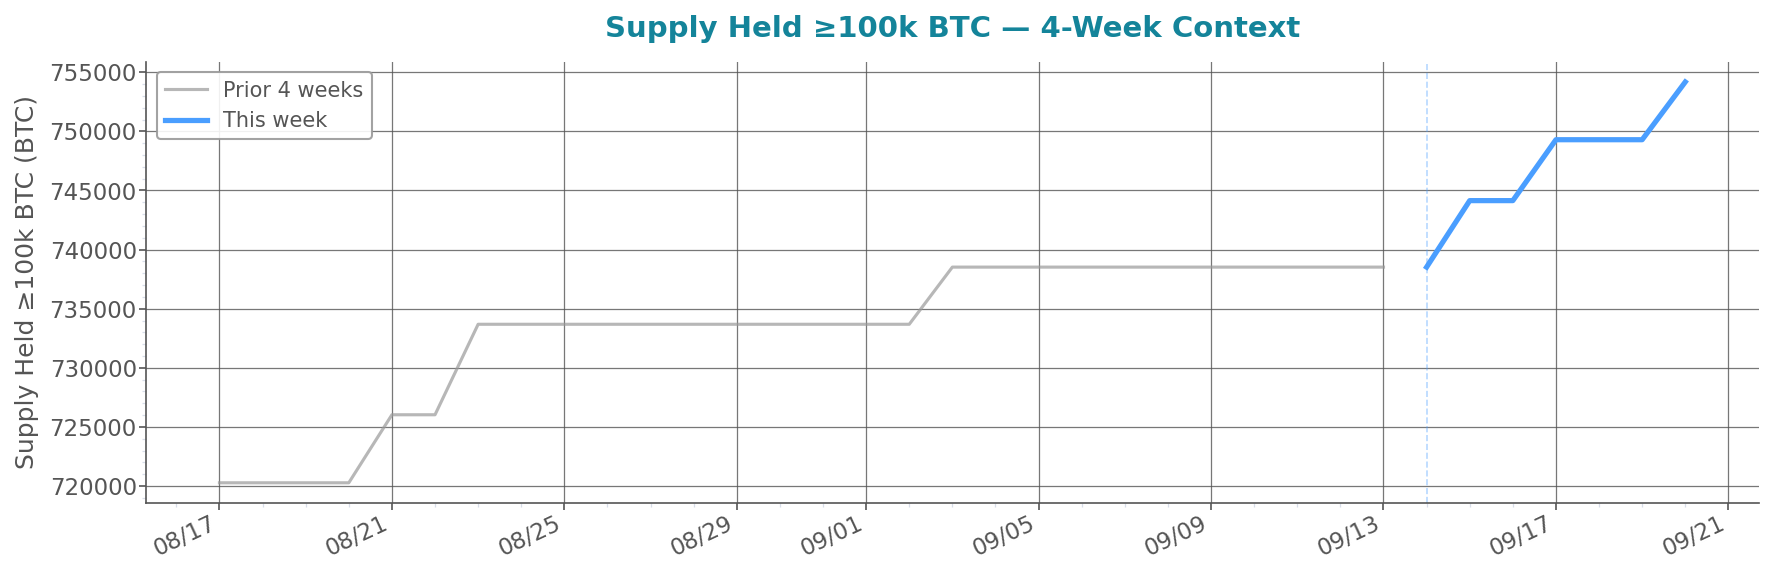
| Supply Held ≥100k BTC | 754,178 BTC | +2.1% | |
| Net Realized P/L | $+99.6M | -46.9% | Coins moved at a profit |
Amber rows deviate >1.5σ from prior 4-week baseline • data as of 2026-09-20
Notable — Supply Held ≥100k BTC: 3.3σ above 4-week baseline
Notable — Perp Open Interest: 2.0σ above 4-week baseline

Weekly Market Wrap
US equities finished the week mixed as markets digested the Federal Reserve's 25 bp rate hike and the prospect of further tightening. The Nasdaq Composite gained 0.72%, supported by technology stocks, while the S&P 500 fell 0.08% and the Dow Jones declined 1.69%. Rising Treasury yields remained a headwind for equities, with the 10-year Treasury yield closing around 5.0%.
European equities were relatively resilient, with the FTSE 100 and Swiss Market Index both posting small weekly gains. At the single-stock level, Illumina and CrowdStrike were among the strongest performers, while Comcast and Schlumberger were among the notable decliners.
In Japan, the Bank of Japan raised its policy rate by 25 bp to 1.25%, its highest level in more than three decades. The decision was accompanied by two dissenting votes, tempering expectations for rapid further tightening. The yen nevertheless weakened beyond ¥157 per dollar following the decision, highlighting the importance of the expected pace of future BOJ hikes rather than the rate increase itself.
Nasdaq also announced plans to introduce 23-hour weekday trading in U.S. equities from December 6. The new session will run from 9 p.m. to 4 a.m. ET, leaving approximately one hour of downtime each trading day. The move represents a significant development in U.S. equity-market structure and expands access to overnight trading.
In crypto markets, Bitcoin and Ethereum saw significant gains, rising 5.59% and 6.24%, respectively, over the week. Regulatory developments remained a key theme after the CLARITY Act failed to advance in the Senate, although crypto markets subsequently recovered. With the bill stalled, attention has shifted toward regulatory action by the SEC and CFTC. The CFTC has submitted a crypto-market rulemaking proposal to the White House for review, while the SEC has also moved forward with measures affecting digital-asset markets.
The expansion of crypto-native derivatives into traditional financial markets also continued. Binance launched its first 24/7 FX perpetual contract, tracking USD/BRL, on September 21, allowing continuous trading outside traditional FX market hours. Coinbase, meanwhile, filed with the CFTC to list perpetual futures tied to individual U.S. stocks, potentially bringing regulated single-stock perpetuals to U.S. markets later this year, subject to approval.
On-chain security was another notable theme. Chainalysis reported a sharp increase in blockchain-assisted cyberattacks, with North Korean and Iranian state-linked operators among those using public blockchains to conceal malware instructions. Chainalysis said blockchain-assisted attacks had increased 440% since the emergence of certain high-capacity open-source AI models.
Looking ahead, the main macro catalyst will be the Trump-Xi summit on September 24, following constructive U.S.-China trade and AI discussions. Markets will focus on progress on tariffs, trade and investment and the implications for global risk appetite. The week will also bring U.S. flash PMIs, new-home sales and durable-goods data, while comments from several Federal Reserve officials will be watched for clues about the timing and extent of further rate hikes.